What Crypto Means for Taxes
I was reminded of a jigsaw with my son recently - the puzzle outgrows the table. Taxes on cryptocurrency feel much the same. The IRS sees digital assets as property, not cash. That single reframing changes everything. If you’re learning how the crypto tax machine actually turns , start with that idea. Before you even think about where to begin investing in crypto , know the tax side waits at the end like a silent gray rhino. Crypto is a digital value token; some call it virtual currency, but the law views it as property when April arrives.
Bitcoin arrived in 2009. Today there are thousands of these tokens. The IRS does not call them currency for tax purposes; they say property, akin to a share or a plot of land. That means ordinary property tax rules apply. You must track what you paid for each coin - that record is your cost basis. FinCEN and others have their own definitions, but for filing, property is the label that matters. Roughly 55 million Americans own crypto, about 21% of adults, so this puzzle touches a lot of folks.
Why Taxes on Cryptocurrency Trip People Up
The big trap is assuming no 1099 means no tax. Many folks believe if no form lands in the mailbox, no tax is owed. That’s wrong. Studies place somewhere between 55% and 95% of crypto holders worldwide failing to report correctly. In one large study, 88% failed to report taxable crypto income at all. The IRS has gathered sizable sums in unpaid crypto taxes, and enforcement keeps widening. New reporting rules are rolling out; the days of flying under the radar are ending, much like the snow melting at the edges.
The traits that make crypto seductive - speed, self-custody - can later make you brittle at filing time. I call this the founder’s curse. You control your coins, but you also carry the record load. Don’t skip this part: if you traded coins, you likely owe something. The tax code doesn’t care how cool the tech is; it cares about gains and income. A blind spot in your ledger can turn into a fine faster than you can say ‘blockchain.’
Beginner guide to crypto taxes and reporting
How the IRS Sees Your Crypto
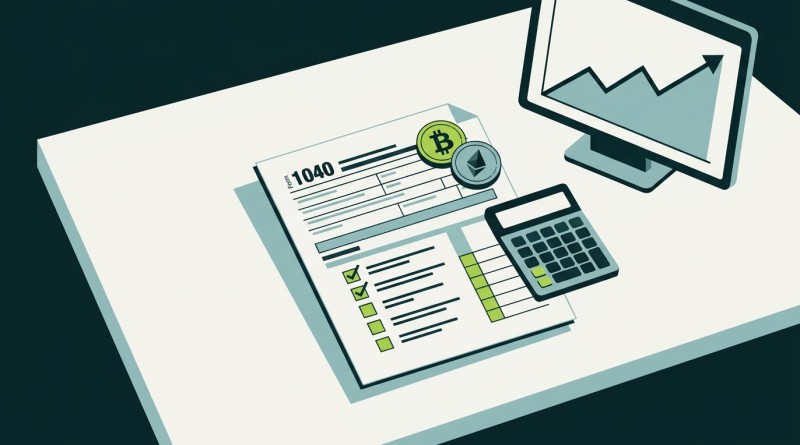
Under IRS Notice 2014-21, virtual currency is treated as property for federal tax. That rule has held since 2014. Every digital asset falls under it, from Bitcoin to stablecoins to NFTs. Because it is property, the same tax logic for stocks applies. Sell Bitcoin at a profit, you owe capital gains - same as selling a share. The AICPA calls crypto long-lived intangible assets, but the IRS label is the one that counts at filing.
The fundamental principle: the IRS treats cryptocurrency as property, not currency.
You must track your cost basis for every unit. The gain or loss is the gap between what you paid and what you received when you sold or traded. Even swapping one crypto for another - Bitcoin for Ethereum, say - creates a taxable event. Many investors wrongly think they owe only when dollars touch their hands. Not true. Spending coins at a shop is also a disposal. The tax logic follows the property, not the form of payment.
The Digital Asset Question on Your Return
Since the 2019 tax year, the IRS placed a digital asset question on the front page of Form 1040. You must answer yes or no; there is no skip. Answering no when you should say yes is a false statement on a federal return. The question asks if you received, sold, exchanged, or disposed of any digital asset. The wording shifts slightly over time, but the screen is always there. This form that captures your crypto tax footprint is a tool the IRS uses to catch non-reporters.
Answering "No" when the answer should be "Yes" is considered a false statement on a federal tax return.
If you received crypto as pay, or staked and earned rewards, you check yes. If you only bought and held, you might check no. But be careful. Moving coins between your own wallets is not a taxable event, yet you still need records. The IRS uses this question as a screen, matching it with forms from brokers. Lying here is a federal offense, so read it closely.
What Counts as a Taxable Event
Knowing which moves trigger tax saves costly mistakes. I’ll list the big ones from the source. This is core to reporting crypto for tax for any normal person. A taxable event is any time you dispose of the asset or receive it as income. The list below covers the common ones folks miss.
Common taxable crypto moves
- Selling crypto for fiat like USD or EUR
- Trading one crypto for another, BTC to ETH for example
- Spending crypto on goods or services
- Receiving crypto as payment for work, taxed as ordinary income
- Earning staking or mining rewards, taxed as ordinary income when received
- Getting airdrops or hard fork tokens you control, ordinary income at fair value
- Earning DeFi yields or interest through lending platforms
- Using crypto as collateral in some DeFi swaps that count as disposal
On the flip side, some moves don’t trigger tax. Buying crypto with dollars is not taxable until you later sell. Moving coins between your own wallets is not taxable, though fees might count. Gifting under the yearly limit is fine. Donating to charity is not a taxable disposal. Simply holding, with no sale, brings no tax on paper gains. Soft forks with no new asset are not taxable either. Loans backed by crypto are usually not taxable, but the swap inside some DeFi loans might be.
Congress crypto tax bills and IRS reporting
Getting Income From Crypto
Crypto you receive as pay, mining, staking, airdrops, interest, or hard fork tokens is ordinary income. The value is set at fair market price on the day you got it. Rates run like short-term brackets, from 10% up to 37%. If you mine as a business, you can deduct power and gear. If it’s a hobby, no deductions. Staking might be self-employment income if steady, needing Schedule C. Employees paid in crypto get a W-2 with dollars figured from coin value on pay date.
Even free airdrop tokens count. You pay tax on them when you gain control, even if you never asked. Later, if you sell those tokens, you owe capital gains on any rise. Hard forks that give new coins are income at receipt. Soft forks with no new asset are not taxable. These rules surprise people, but they are clear in the source. Mining as a hobby goes on Schedule 1, while a mining business uses Schedule C. Either way, the day you receive the coin sets the income number.
Capital Gains and How Much Tax on Crypto Profit
When you sell or trade crypto for more than you paid, you owe capital gains. The rate hinges on how long you held. Held one year or less is short-term, taxed as ordinary income. Held more than one year gets preferential rates. The long-term capital gains rate for crypto can be 0%, 15%, or 20% based on your income. That’s the long-term capital gains break for crypto that rewards patience.
So how much tax you owe on crypto profit depends on your bracket and hold time. Example: you bought 1 ETH for $2,000 and sold at $5,000. Gain is $3,000. If held six months, you might pay 22% federal, about $660. If held fourteen months, you pay 15%, about $450. Waiting saved $210 - a neat illustration of the patience premium. Higher earners may owe an extra 3.8% net investment tax. NFTs seen as collectibles can hit 28% max long-term rate. Capital losses can offset gains and up to $3,000 of ordinary income a year, with carry forward.
NFTs and Collectibles Rules
From a tax view, NFTs act like crypto. Buying an NFT with crypto is a disposal of that crypto, causing gain or loss. Selling the NFT later triggers gain on price change. Minting as a creator is self-employment income. The IRS says some NFTs - art or profile pics - may be collectibles taxed up to 28%. Collectors buying are not taxed until sale. Digital art pieces could fall in that bucket, so watch the label.
NFTs classified as collectibles may be taxed at up to 28% maximum long-term capital gains rate.
DeFi and the Tricky Stuff
Decentralized finance makes tax work hard. Every token swap on a decentralized exchange is a taxable event. Trading ETH for USDC needs gain math. Providing liquidity might be seen as a taxable swap by careful folks, though guidance is unclear. Gas fees can add to cost basis or cut proceeds. DeFi lending interest is ordinary income. DAOs have no clear IRS rule yet, but likely flow-through. Margin and futures trading likely count as capital gains, though explicit guidance is missing.
Even big centralized platforms follow the same base rules. If you use something like PayPal’s crypto tax reporting , they still send forms but you must check yourself. The key is each move is a possible tax moment. Don’t let the tech blur that. Foreign exchanges matter too: if your aggregate value exceeds $10,000 at any point, you may need an FBAR. Lost or hacked crypto is not deductible after the 2017 tax law change, so insurance or caution beats a write-off.
Keeping Your Records Straight
Under new IRS rules, you must track each wallet separate. The old universal wallet pool is gone. You calculate cost basis per wallet or account. This makes good logs a must. Some people use tools like Merlin for crypto tracking to help. You can also find free crypto tax reports from some software if your case is simple. Record every transfer, even between your own wallets, because fees can be a taxable disposal.
Record date bought, date sold, cost basis with fees, sale price minus fees, fair value at receipt for income, and which wallet. Accounting methods matter: FIFO is default, but LIFO or HIFO can save tax in rising markets. Specific ID needs tight records. If your 1099 lacks basis, you can submit your own with proof. Exchange fees and gas fees related to buying add to basis; fees on selling subtract from proceeds. Scott bought $300 BTC plus $10 fee, basis $310, sold $400, gain $90. Simple math, but only if you wrote it down.
New Reporting Forms and Deadlines
Brokers now must send new Form 1099-DA for crypto sales and exchanges. They report gross proceeds, and later covered assets basis. Decentralized platforms are exempt for now, but you still must report all. Exchanges may send 1099-MISC for over $600 of ordinary income like staking. The IRS matches these forms with your return automatically. Blockchain analysis can link wallets to you. Good-faith reporting gets some relief, but the taxpayer still must be accurate.
Key forms for crypto filers
- Form 1040 with digital asset question on front
- Form 1099-DA from brokers for sales
- Form 1099-MISC for staking or airdrop income over limit
- Form 8949 and Schedule D for capital gains
- Schedule 1 or C for ordinary crypto income
- Form 8283 for donations over $500
The tax filing deadline stays April 15, with extension to Oct 15. Extension to file is not extension to pay. If you forgot past crypto, amend with Form 1040X. Better to fix in good faith than wait for a letter. Failure to report on purpose is fraud, with heavy fines and prison risk. The IRS sends warning letters to suspected holders; some need response, some are just info. Don’t ignore them.
2025 crypto tax updates from Karlton Dennis
State Sales Tax and Crypto
At state level, only 11 states give sales and use tax guidance on crypto. They include California, Kansas, Kentucky, Michigan, Minnesota, Missouri, New Jersey, New York, Tennessee, Washington, and Wisconsin. Only five give income tax guidance: Illinois, Michigan, New York, New Jersey, Wisconsin. Rules vary. California says paying with crypto is a sale subject to sales tax. Pennsylvania taxes NFT transfers. Clear law is needed as confusion breeds audits. Illinois treats digital goods without tangible property as outside certain taxes. Indiana may tax specified digital products.
Common Mistakes to Avoid
I see the same errors repeat. Here’s a plain list so you don’t fall in. Good crypto tax reporting means dodging these. Most folks get caught by the simple stuff, not the weird DeFi loops. Keep your eye on the basics and you’ll be fine.
Top crypto tax mistakes
- Not reporting crypto-to-crypto trades, the most common miss
- Assuming no 1099 means no taxes, still required to report
- Cost basis errors, guessing instead of using buy price plus fees
- Forgetting staking and mining income as ordinary income
- Ignoring airdrops and hard forks that count as income
- Poor record-keeping, now worse with wallet-by-wallet rules
- Not reporting losses that could cut your bill
- Using foreign exchanges over $10k without FBAR filing
- Mismatched info between return and 1099 forms
- Incorrect cost basis calculations from averaging
Another big one is thinking you won’t get caught. The IRS uses automated systems and can match wallets. If they send letters like 6174 or 6173, pay attention. The first is info, the second needs response. Intentional skip is tax fraud, with fines up to $250,000 and five years prison. That’s a heavy price for a puzzle you could have solved with a spreadsheet.
Ways to Stay Compliant and Lower Your Bill
Hold long-term for lower capital gains rates. Tax-loss harvesting works since crypto has no wash sale rule yet; sell at loss, rebuy, claim it. You can offset gains or up to $3,000 ordinary income a year, carry the rest. Self-directed IRA holds crypto tax-free or deferred. Donate crypto to charity for deduction without capital gains tax. These moves are legal and smart if done right.
Reconcile your 1099-DA with own logs. Double-check proceeds and compute your own cost basis. If you run complex DeFi or big portfolios, get pro help. The goal is clean crypto tax reporting without the stress. Taxes on cryptocurrency don’t have to be a blind spot in your ledger if you read the label from inside the jar. Start with one wallet, one year, and a plain note of what you paid. That’s the antidote to the founder’s curse.
Wallet by Wallet Math
I want to stress the wallet rule again. You can’t lump all Bitcoins together across exchanges. Each account is its own pool. This change makes detailed records essential. If you moved coins between platforms, the basis may be missing on forms. You can fix with your own docs. Don’t panic, just track. Henry bought BTC at three prices and sold one; the gain differs hugely by method. The separate wallet view stops you from mixing those pools by accident.
Cost Basis Methods Explained
FIFO means first coin bought is first sold. LIFO means last bought sold first, can save tax when prices rise. HIFO sells highest cost first. Specific ID lets you pick exact units but needs logs. Example: buy BTC at $15k, $50k, $40k, sell one at $15k. FIFO gain zero, LIFO loss $25k, HIFO loss $35k. Big difference. Another case: buy 1 BTC at $28k, 1.5 at $70k, 0.5 at $29k, sell 0.5 at $32k. FIFO gain $18k, LIFO gain $3k. The method picks your tax bill.
Ways to pick which coins you sold
- FIFO, default first in first out
- LIFO, last in first out
- HIFO, highest cost first out
- Specific identification with detailed records
Most tax software lets you switch method per account. But once you file, consistency matters. The method must be clear to the IRS if asked. Missing basis on a 1099-DA is common after wallet moves; you can attach your own numbers with proof. If you truly can’t estimate, the whole proceeds may count as gain, so guess close is better than nothing. Keep the pics of trades if you have them, they help later.
Comments on “When the Crypto Ledger Becomes a Blind Spot: Taxes on Cryptocurrency and Reading the Label from Inside the Jar”
No comments yet. Be the first to share your thoughts.